How to Teach Kids the Value of Money: A Canadian Parent's Guide
A practical Canadian guide: give your child a small amount to manage, agree what it covers, and talk about their choices each week. Grade-by-grade ideas.
By Mark Sharma · October 15, 2026
Short answer: Give your child a small amount of money they can make real choices about. Agree on what it covers, then talk about their decisions each week. They choose how much to spend, save or give, and reflect on how it went. You provide guidance and boundaries, with responsibility growing alongside their understanding.
Money is easy to overlook behind a tap or an app. Make it visible through small, real decisions. Children need practice noticing what they have, what a purchase changes and whether it was worthwhile. Those experiences prepare them for bigger decisions and, eventually, their first paycheque.
Your child does the learning through those choices. Your role is to help them see the consequences, explain what they don't understand and return to the conversation. A small amount managed repeatedly gives you something concrete to talk about together.
What "the value of money" means to a kid
Before my boys had money of their own, the question was usually "Can you buy this for me?" Less than a week after our first Monty O'Clock, my older son asked me in a grocery store, "Do I have enough money in my Spend Jar to buy a Hot Wheels car?"
He was taking responsibility for part of the decision. That shift comes through experience: choosing, waiting, running out and deciding afterward whether something was worth it. Giving children some money to manage lets them experience those consequences while the amounts are small.
Start with money your child can manage
The Financial Consumer Agency of Canada (FCAC) explains that allowance is an opportunity to learn money management; the amount matters less than the purpose.
Weekly allowance, birthday money, gifts from relatives or an occasional amount you set aside can all provide practice. What matters is that:
- It's theirs to decide about, within limits agreed in advance.
- It's affordable for your family, so a poor choice stays a manageable lesson.
- The arrangement is clear. If you give an allowance, keep the schedule predictable. With occasional gifts, plan around money already received.
Choosing an amount that works
Start with your budget and the responsibility you're handing over. Ask:
- What do you already spend on small extras that could become their money?
- What amount can you provide consistently without strain?
- What could they buy soon, and what would require saving?
| Weekly amount | Over 52 weeks | Possible use |
|---|---|---|
| $5 | $260 | Small extras, with some money saved toward a goal |
| $10 | $520 | A larger agreed spending responsibility, alongside saving and giving |
The annual total can help you decide how much existing spending to hand over. It doesn't need to be additional spending. If the arrangement becomes difficult to afford, discuss a change before the next payment and help your child adjust their plan.
Decide what the money has to cover
Before the first payment, agree on two lists.
What you'll keep paying for: essentials such as food, clothes, school supplies, health and safety needs, plus activities you've agreed to cover. Lunch and warm boots should never depend on their Spend balance.
What their money covers: agreed extras, such as treats, small toys, game add-ons, gifts or a goal they've chosen.
On that grocery trip, my younger son put back a Hot Wheels car when I reminded him it would come from his Spend Jar. Then he asked, "Do I have to pay for the pineapple from my Spend Jar?" No: the pineapple was on my list. He was working out the boundary between his money and family money.
Write a short agreement where you can both see it:
- How much money, and how often.
- What you cover and what their money covers.
- Purchases that need permission, including in-app spending.
- What happens when their Spend money runs out.
- When you'll check in together.
Keep the boundaries consistent. If you routinely buy the agreed extras when their jar is empty, its balance stops meaning much.
Let each dollar have a job
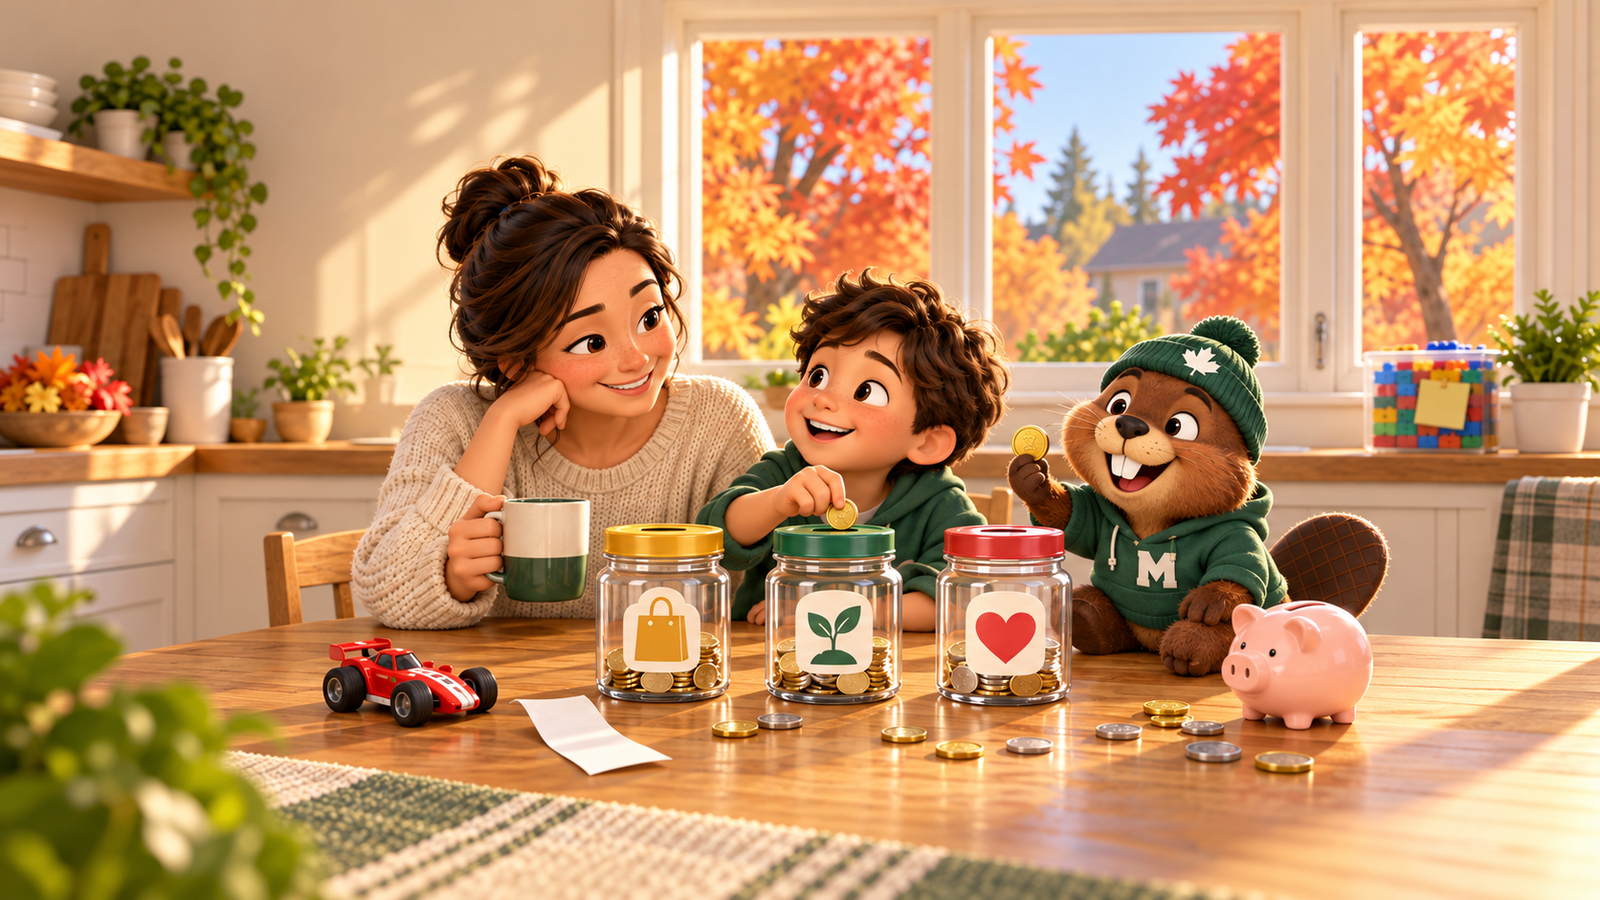
Split money into Spend, Save and Give. Jars, envelopes or columns on paper all work.
- Spend: money for the extras you've agreed they can choose.
- Save: money for a goal they care about.
- Give: money to share with a person or cause.
Let your child choose the split, with your guidance. Whole dollars can make the choice concrete: "Two dollars to Save and three to Spend."
Then ask, "Why?" After a few weeks, my older son put $8 of his $10 toward his LEGO goal and $1 each into Spend and Give. He explained that he wanted to reach his goal faster and already had money in Spend. He had considered what he had and what mattered most. That explanation was the skill.
Giving deserves a conversation too. Let them explore who or what they want to help and why. Keep money set aside until they choose, then involve them in making the gift and seeing what their contribution supports.
Working out how long a goal will take
Illustrative example: Leo receives $5 a week and wants a $20 LEGO set. Starting with nothing saved, putting $2 a week into Save takes 10 weeks.
Include the full purchase price. In Ontario, 13% HST brings that $20 set to $22.60. At $2 a week, Leo needs 12 weekly deposits. Use the applicable tax where you live, and include delivery if needed.
Let your child help calculate the timeline. What changes if they save more each week or add money earned from a job?
Be specific about trade-offs. Buying something entirely from Spend doesn't automatically delay a goal funded separately through Save. If they want to move savings into Spend or change future contributions, work out the effect together. Show the consequence of the choice they're actually making.
When my son saw that his $200-plus LEGO goal would take about 26 weeks at his saving rate, he shouted, "Twenty-six weeks?! Oh my gosh!" I asked whether he still wanted it. "Oh yeah. It'll be worth it!" He was connecting the amount, the wait and the value he placed on the goal.
Their money, your guidance
Your child makes decisions within the boundaries you've agreed. You're still the parent, and sometimes "not today" is appropriate. Explain your reason and connect it to those boundaries.
Children get excited and forget the drawer full of similar toys at home. Help them slow down and consider the consequences:
- "Here's how long it takes to refill." Divide the proposed purchase cost by what they add to Spend each week. My son was putting $1 a week into Spend; using his remaining balance would have taken about 45 weeks to replace at that rate.
- "If Spend is empty, I won't buy those extras for you." Return to the agreement you made together.
- "Let's look at what you already have." Once we got home, my son forgot about the toy he'd wanted.
- "Let's take a picture and come back to it." Agree on a waiting period, then revisit whether they still want it.
Ask, "What changes if you buy this?" or "Will you still want it tomorrow?" If the purchase fits your agreement and they still want it, give them room to decide.
When my son asked about the Hot Wheels car, I confirmed he had enough money and asked whether another car was worth spending his money on. He looked through the cars and walked away. He made the decision.
Avoid "That's a waste of money" or "You'll regret it." Help your child form a judgement through experience.
If you disagree about a purchase, return to the agreement. A new restriction is worth discussing explicitly. Children need to understand which choices are theirs and which require your permission, so they can plan with confidence.
After the purchase: was it worth it?
Return to a purchase a few days or a week later:
- What did you buy?
- How much have you used it?
- Was it worth it?
- Would you choose it again?
Listen without steering toward regret. My younger son decided a pack of gum wasn't worth it and wouldn't buy it again. My older son liked his PEZ dispenser and would buy another. Both were learning to judge value from their own experience.
Sometimes the lesson arrives naturally. A Needoh toy my son bought started leaking a couple of weeks later, and we'd thrown out the receipt. That gave us a practical reason to discuss keeping receipts.
A disappointing purchase doesn't need a lecture. Ask what they would check or do differently next time, then let that answer inform the next decision.
Build money skills early. Practise them as life gets bigger.
Introduce the fundamentals early: money has limits, purchases involve choices, and earning involves creating value. Revisit those ideas with increasing depth. Use these grades to guide examples and parental support, building on what your child can explain and practise. These are starting points, not developmental rules or curriculum requirements. Move up or down depending on what your child is ready for.
Kindergarten
Skills to practise: spending choices with support, comparing a price with available money, noticing what's left and beginning to reflect on purchases.
Guide for parents: use real coins alongside their jars. Ask, "You have $5. This costs $3 altogether. What will be left?" Let them decide on a small purchase. Later, ask, "Have you enjoyed it? Would you buy it again?" Explain that tapping a card still uses money.
When my younger son emptied his piggy bank to add it into Monty, he sorted the coins, discussed their values and did most of the adding himself.
You can read the price and help with counting while your child makes the decision. Ask them to show their thinking with coins or explain it aloud; the conversation can go beyond what they can read independently.
Grades 1–2
Skills to practise: splitting money, comparing two wants, working toward a goal, recognizing different payment methods and connecting useful work with earning.
Guide for parents: let them explain and adjust their split. At checkout, connect the payment to their balance. Ask, "Can you afford it, and do you want it enough to spend your money?" Explain that debit uses money in an account, while credit involves borrowing. Offer an optional paid job with a clear task and agreed payment.
When you pay for their purchase on your card, record the agreed amount against their Spend money. Ask, "What was your balance before, and what is it now?" The payment method doesn't create extra spending money.
Grades 3–4
Skills to practise: calculating how spending changes a goal, comparing prices and expected use, understanding repayment, completing paid jobs and recognizing basic privacy risks.
Guide for parents: use their actual Spend balance and goals. Include tax and delivery costs. Explore pretend borrowing: "If you use next week's money today, what will be available next week?" Help them request payment for completed work. Practise keeping passwords and PINs private and asking you about suspicious requests.
When my older son chose his LEGO goal, he remembered the money in his piggy bank and the money he'd earned helping with his grandma's yard work. They stopped being separate piles. It was all his money.
Grades 5–6
Skills to practise: longer plans, earnings after costs, recurring charges, basic interest and the difference between money owned and money owed.
Guide for parents: give them a defined budget for agreed extras. Turn a monthly subscription into its yearly cost. Help them price a job, subtract supplies and write a simple invoice. Introduce net worth, what you own minus what you owe, through a hypothetical example. Review purchases without treating regret as failure.
Grades 7–8
Skills to practise: longer budgets with less prompting, digital spending, persuasive offers, saving versus borrowing, and boundaries around money and friends.
Guide for parents: hand over an agreed category, such as entertainment, within a clear limit. Track digital purchases together. Use hypothetical repayment examples to show how minimum payments can leave debt outstanding and increase total interest costs. Discuss gifting, lending and peer pressure. Ask, "What future money are you committing, and what happens if your plans change?"
Make it a two-minute weekly routine
Choose a regular time, such as Saturday breakfast or Sunday evening. Keep the check-in short and return to familiar questions:
- What came in, and where did it come from?
- What's available, and what's already committed?
- What do you want your money to do next? Choose the split and explain why.
- Was your last purchase worth it?
- What could you do to earn or create value?
Use the questions that fit the week. A deeper conversation or activity can happen separately; the two-minute check-in keeps decisions connected.
No new money? Skip the split and review a goal or purchase. No new goal? That's fine. After reaching a goal, my younger son said he wanted "nothing yet". Give money can wait too: my older son set money aside for sharks and is still choosing where to give it.
A few days after buying the toy he'd saved for, my younger son asked on a Tuesday, "Is it Monty O'Clock today?" He was beginning to anticipate the routine. Siblings can join the conversation too: he sat beside his brother through the whole "45 weeks to refill" discussion.
Building toward a first paycheque
Each year, transfer a little more responsibility: a larger budget, a longer goal or a spending category you previously managed. Keep returning to allocation, planning, reflection and protecting money.
Introduce earning alongside allowance. Agree which tasks are everyday family contributions and which extra jobs can earn payment. Discuss what a job helps someone accomplish, what good work looks like and what it costs to complete.
For an older child, follow a job through from agreement to payment: describe the work, agree the price, complete it and request payment. A simple invoice can list the job, date and amount. Then discuss how to allocate the earnings.
By their first paycheque, the aim is for these habits to feel familiar. They've practised deciding what money should do, experienced worthwhile and disappointing purchases, and learned to connect earning with creating value.
Practise it at Monty O'Clock
I built Monty to help families keep this routine. At a time you choose, your child reviews what came in, splits money between Spend, Save and Give, checks goals and reflects on purchases. They make decisions with you beside them.
Monty tracks the allowance and gifts you provide in cash or by transfer. It doesn't hold money, issue a card or connect to your bank.
You set the allowance amount and schedule. An occasional bonus can recognize extra effort, with a note explaining why. Treat every recorded dollar as real money your child can count on when they choose to use it. Keep the amount sustainable and honour the arrangement you've agreed.
Read our family's first 10 weeks with Monty.
Explore Spend, Save, Give, saving goals, purchase reviews, allowance habits and how Monty O'Clock works.
Start the Monty O'Clock Monthly Challenge: your first four Monty O'Clocks are free, with every feature and no credit card needed. After that, Monty is $10/month or $99/year, plus applicable tax. See pricing for details.
Questions parents ask
What if we don't give a weekly allowance?
Gift money or occasional amounts work too. Make clear which money your child controls, help them plan around what's available and keep the conversation regular.
If it's their money, can I still say no?
Yes. Explain the reason and connect it to your agreed boundaries. Give your child room to make everyday choices, while providing context and oversight.
What if my child spends everything right away?
If the purchase fits your agreement, let them experience the result. At your next check-in, ask whether they'd choose differently. Continue covering essentials while holding the boundary around agreed extras.
Can I reward my child with extra money?
Yes. Explain the extra effort or completed job the payment recognizes. Keep everyday responsibilities clear. Once it's in their jar, it's theirs to use.
Sources
- Financial Consumer Agency of Canada, Teaching children about money, checked October 14, 2026
- Financial Consumer Agency of Canada, Using debit cards, checked October 14, 2026
- Financial Consumer Agency of Canada, Module 3: Understanding credit, checked October 14, 2026
- Financial Consumer Agency of Canada, Paying off your credit card, checked October 14, 2026
- Mark Sharma (Monty), Our family's money habits with Monty, checked October 14, 2026
- Monty, Monty pricing, checked October 14, 2026
Take the Monty O'Clock Monthly Challenge!
Your first four Monty O'Clocks are free. No credit card needed.