How to Start an Allowance: Your Child's First Money to Manage
Start your child's first allowance in six steps: find the money, agree what it covers, pick a payday, fit chores in, talk on payday, adjust after a month.
By Mark Sharma · October 15, 2026
Short answer: Pick an amount your family can keep paying, often money you already spend on your child's small extras. Agree in advance what it covers and what you'll still pay for. Choose a payday you can stick to, and let your child decide what each dollar does: spend, save or give. After a month, adjust the setup together.
An allowance doesn't have to be new spending. For many families it's the treats, small toys and game add-ons you already buy, with your child now making the decisions. Their first paycheque shouldn't be their first chance to manage money.
The Financial Consumer Agency of Canada (FCAC) puts it simply: the goal of an allowance is to teach children how to manage money, and the amount matters less than that goal.
Step 1: Find the money you already spend
Before choosing a number, look at what you spend now on your child's extras. For a few weeks, notice the treats at checkout, small toys, app purchases and "just this once" requests.
Illustrative example: a family notices they spend about $40 a month on one child's small extras. Over a year that's $480, or a little over $9 a week. They decide to give $9 a week and stop buying those extras on request. The total spending barely changes. Who decides is what changes.
You don't have to redirect everything, but the amount should be enough to matter. Your child needs enough to face real choices: buy now or save, this or that. Making those decisions while the stakes are low is the point. It should also be an amount you can pay consistently without strain.
The FCAC suggests choosing an amount that suits your child's age and raising it as they grow. A common starting point is $0.50 to $1 a week for each year of your child's age, so $3.50 to $7 a week for a seven-year-old. It's a guide, not a rule: pick what fits your family.
Step 2: Agree what the allowance covers
This is the step that makes an allowance work. Without it, your child's money and your money blur together, and the balance stops meaning much.
Agree on three lists before the first payday:
- You keep paying for: food, clothes, school supplies, health and safety, and activities you've agreed to cover.
- Their allowance covers: agreed extras such as treats, small toys, game add-ons, gifts for friends or a goal they choose.
- Needs your permission first: in-app purchases, anything over an amount you set, or anything you'd want to check for safety.
Then agree what happens when their Spend money runs out: no more extras until next payday. Essentials never depend on their balance.
Expect the boundary to be tested early; that's part of learning it. Less than a week after our first Monty O'Clock, my younger son put back a toy car when I reminded him it would come from his Spend Jar. Then he asked whether he had to pay for the pineapple too. No, the pineapple was on my list. He was working out where his money stopped and family money began.
Write the agreement somewhere you can both see it. A sticky note on the fridge is enough.
Step 3: Pick a payday you can keep
A predictable payday lets your child plan. If allowance arrives "whenever," they can't work out how long a goal will take or whether to spend today.
- Weekly is a simple place to start, especially with younger children.
- Every two weeks or monthly is an option as your child gets older. It gives them practice making money last longer.
Choose a day and time you'll reliably be around, such as Saturday breakfast. We do ours on Saturday. Later that summer, my younger son asked on a Tuesday whether it was Monty O'Clock yet.
If you miss a payday, pay it as soon as you can and say so. A skipped payment that nobody mentions teaches that the arrangement doesn't really count.
Step 4: Decide how chores fit (your choice)
Families handle chores differently, and there's no single right approach. Three common setups:
- Allowance separate from chores. Everyday contributions, like tidying up or setting the table, are part of family life. The allowance is for learning to manage money.
- Base allowance plus paid extra jobs. The allowance stays steady. Extra jobs beyond everyday contributions, such as washing the car, can earn more.
- Allowance tied to chores. Money is paid for agreed tasks.
Whichever you choose, make it clear in advance and keep essentials separate from it. The FCAC notes that as children get older, they may earn money from basic chores or part-time work, and that earning may teach financial responsibility and independence.
If you link money to chores, decide ahead of time what happens when a task isn't done, so the conversation isn't made up on the spot.
My older son already had money from helping with his grandma's yard work. When he chose his first savings goal, he remembered that money and the money in his piggy bank. Earned money and allowance became part of the same plan.
Step 5: Make the first payday a conversation
On the first payday, sit down together for a few minutes:
- Show the money and name the amount. "Your $7 for this week is in."
- Let them choose its jobs. How much to Spend, Save and Give? Whole dollars keep it concrete. You can guide, but the split is theirs.
- Ask why. "What made you choose that?" Their reason is the skill.
- Pick a goal, if they want one. Something to save for makes waiting meaningful. "Nothing yet" is fine too.
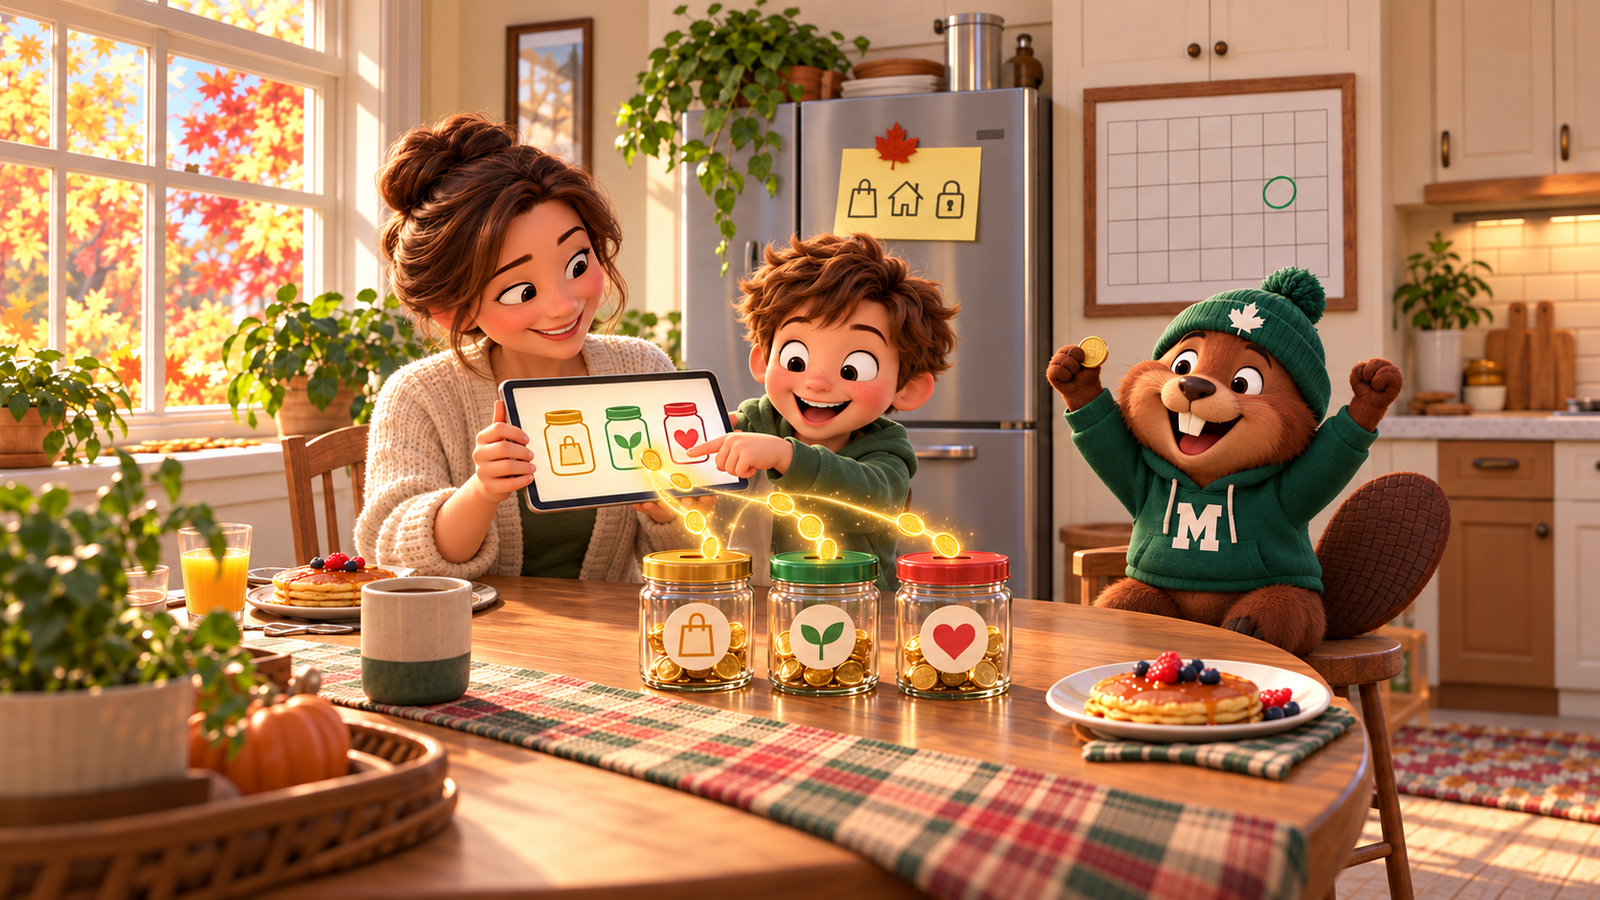
The money doesn't have to change hands. It can stay in your bank account while you keep a record of what's in each of your child's jars. When they buy something, you pay and take it out of their Spend balance. Cash in physical jars, envelopes or a notebook work too. What matters is that your child can see what they have in each.
After my younger son's first Monty O'Clock, he wanted to do it again the next day.
The first month: what to expect
Expect a few early tests. Your child may spend everything in the first week, ask you to buy something their allowance now covers or want to change the split as soon as they see a toy.
- If they spend it all: let the agreement stand until next payday. At your next check-in, ask whether they'd choose differently.
- If they ask you to buy an extra: point back to the agreement. "That's a Spend Jar thing. Do you want to use your money?"
- If they want something big: work out together how many paydays it takes.
You're still the parent. If a purchase fits the agreement, give them room to decide. If it doesn't, explain why using the boundaries you agreed.
Step 6: Adjust the setup after a month
After four or five Monty O'Clocks, and no later than week five, check in on the arrangement itself, not just the money. Monty O'Clock happens every week, even if payday is every two weeks or monthly, so the review still comes after about a month. Ask:
- Is the amount working for your budget and their responsibilities?
- Is anything on the "their allowance covers" list causing friction?
- Do they want to adjust their split or their goal?
- Is the payday still realistic for your family?
Make any change before the next payment and explain it. Over the years, hand over a little more: a bigger amount, a longer gap between paydays or a new category they manage, such as their own entertainment.
The FCAC also suggests discussing with your child when an allowance will stop, for example when they get a job, and being clear about which expenses you pay for and which you expect them to cover.
Adapting it by grade
These are starting points, not developmental rules. Adjust them to your child.
- Kindergarten: a small amount with coins they can hold, one simple choice and a weekly payday. You read prices and help count.
- Grades 1–2: a weekly allowance, a short savings goal and a clear list of what it covers. Talk through each split.
- Grades 3–4: add a longer goal and include tax in prices. Consider paid extra jobs alongside the base allowance.
- Grades 5–6: try every two weeks. Add a category, such as gifts for friends' birthdays, that they budget for themselves.
- Grades 7–8: consider monthly. Hand over a larger category, such as entertainment, and include digital purchases in the agreement.
Practise it at Monty O'Clock
Monty gives the allowance a regular home. You set the amount and choose a weekly, bi-weekly or monthly schedule. At Monty O'Clock, the two-minute weekly check-in, your child sees what came in and chooses how much goes to Spend, Save and Give. They check their goals and review purchases. You can add an occasional bonus for extra effort, with a note saying why.
Monty is the record, not the bank. The money stays in your account, and you make the purchases. Monty keeps track of what's in each of your child's jars, including allowance and gifts. It doesn't hold money, issue a card or connect to your bank.
See how allowance habits work in Monty, or read how Monty O'Clock works. For the bigger picture, start with how to teach kids the value of money.
Start the Monty O'Clock Monthly Challenge: your first four Monty O'Clocks are free, with every feature and no credit card needed. After that, Monty is $10/month or $99/year, plus applicable tax. See pricing for details.
Questions parents ask
What age should kids start getting an allowance?
There's no set age. A good time is when your child can make a simple choice with an adult helping. Choose an amount big enough to make the choice real, and add responsibility as they grow.
What if I can't afford a regular allowance?
Start with money you already spend on extras, or with gift money they've received. A small amount paid reliably is easier to plan around than a larger one that comes and goes.
Should I take away allowance as a punishment?
It's your call. Tying the allowance to everyday behaviour can blur what it's for, so many families keep payday itself separate. If you do use money, treat it as a learning moment with a real cost: if it takes your child a week to add $2 to their Spend jar, losing it in a few moments is a lesson they'll feel. In Monty, you can add an adjustment tagged Correction that takes money out of one of your child's jars, with a reason they can see. For example: they kept being mean to a sibling after repeated requests to be kind. Talk it through, so the lesson is about the choice, not the money.
What if my child wants to spend it all on one thing?
If it fits your agreement, let them. If it's a bigger item, help them work out how many paydays it will take to save for it.
Sources
- Financial Consumer Agency of Canada, Teaching children about money, checked October 15, 2026
- Mark Sharma (Monty), Our family's money habits with Monty, checked October 15, 2026
- Monty, Allowance habits, checked October 15, 2026
- Monty, How Monty O'Clock works, checked October 15, 2026
- Monty, Monty pricing, checked October 15, 2026
Take the Monty O'Clock Monthly Challenge!
Your first four Monty O'Clocks are free. No credit card needed.